
| Price to Earnings | EV/EBITDA | |
|---|---|---|
| FY1 | 12.1 | 6.4 |
| FY2 | 6.4 |
New Leadership Team Takes the Wheel Just as the Gold Market Hits Its Stride
Newmont (NYSE, ASX: NEM) the world’s largest gold producer, generated record free cash flow of US$7.3 billion in FY25 and followed that with another record US$3.1 billion in the 1Q26 alone, supported by rising gold prices and tighter cost controls. The company holds net cash of US$2.1 billion, has launched a US$6 billion share buyback programme, and pays a quarterly dividend of US$0.261 per share. A new leadership team takes over on 1 July 2026, with fresh appointments across finance, operations and project development signalling a sharper focus on execution and disciplined capital spending.
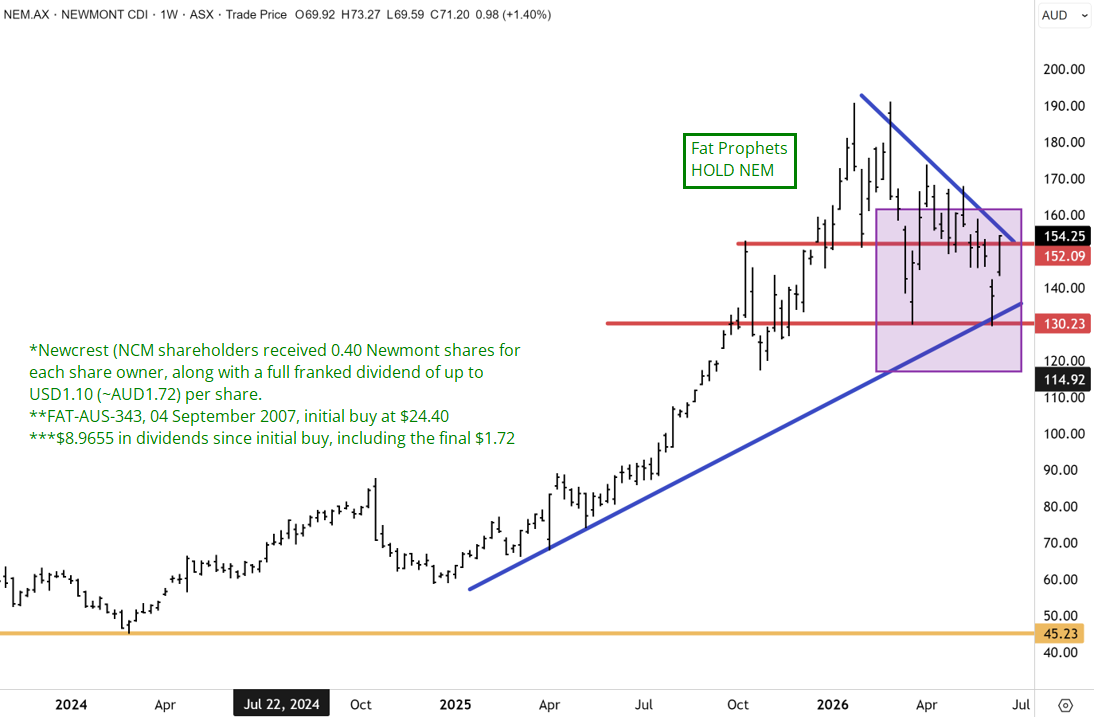
In our last tech update on the 2nd of May, we noted that “Newmont surged to new record highs near A$200. Since then, (ASX: NEM) has corrected sharply to $130 before finding strong support at the primary uptrend. Newmont has since rebounded in recent weeks to above $150. We anticipate new record highs to ensue in 2026, with support very well defined now at $130/140 below, in our opinion.”
Since our last update, Newmont has rebounded off key support at $130, which also intersects with the primary uptrend. Newmont has pushed higher towards $154 and is now encountering resistance at the downtrend. We anticipate a topside breakout and a retest of the next resistance cluster above $160/$170 in the coming months.
Trading Update
Newmont is moving into the next leg of the gold cycle with a refreshed leadership bench, a balance sheet transformed by record free cash flow and growing strategic leverage to some of the most attractive growth options in the sector. The company has announced a new Chief Financial Officer, Chief Operating Officer, Chief Technical Officer and an Executive Vice President for Project Development, all effective 1 July 2026, explicitly framed as the “next phase of delivery” under recently installed CEO Natascha Viljoen, while continuing to generate record levels of free cash flow and signalling a disciplined approach to capital allocation, project execution and shareholder returns. In parallel, a tightening physical gold market, rising central‑bank demand and the prospect of further weakness in the US dollar are creating a constructive backdrop that could allow Newmont’s operating and financial leverage to gold to show through more fully over the next 12–24 months.
The leadership changes are substantial and clearly thought through. On 15 June, Newmont filed an 8‑K and issued a news release detailing a series of executive appointments that will take effect on 1 July: Brian Tabolt becomes Executive Vice President and Chief Financial Officer, Mark Rodgers becomes Executive Vice President and Chief Operating Officer, David Thornton steps into the Executive Vice President and Chief Technical Officer role, and David Fry is promoted to Executive Vice President, Project Development. Viljoen described the new team as bringing together “respected leaders with deep industry experience” across operations, finance, technical and projects, adding that these appointments “reflect the capabilities we need to strengthen performance, advance our world‑class portfolio with discipline and pace, and continue creating long‑term value for shareholders and stakeholders”.
The new CFO, Brian Tabolt, represents continuity in financial discipline rather than an external shake‑up. Tabolt joined Newmont in 2021 and has since held a series of senior roles including Group Head, Financial Planning and Analysis, Chief Accounting Officer and interim CFO; he previously spent more than a decade at Molson Coors as Vice President, Controller and Chief Accounting Officer, after earlier work in technical accounting and SEC reporting at Deloitte. His promotion consolidates responsibility for capital allocation, balance‑sheet management and reporting with an internal candidate who already helped steer Newmont through its recent cash‑flow inflection, giving investors a clearer line of sight on how the company intends to deploy its growing financial firepower.
On the operational side, the appointments of Mark Rodgers as COO and David Thornton as CTO are designed to tighten alignment across a larger, more complex asset base. Rodgers has more than 30 years’ resources experience and has already run Newmont’s Africa, Asia Pacific, Latin America and North America regions at various points since 2020, after prior roles at BHP and Rio Tinto; as COO, he will oversee the 12‑site operating portfolio as well as health, safety, security and environment, with a mandate to drive consistency in performance and standards across jurisdictions. Thornton, with over 25 years in mining including stints at Barrick and Gold Fields before joining Newmont in 2016, will lead Technical Services – exploration, asset management, processing, mine planning and digital – with a focus on improving project performance and accelerating technology and innovation, which is increasingly critical as the company seeks to squeeze more ounces at lower costs from both established and new operations.
The creation of an executive‑level Project Development role reflects how central high‑return growth options are to Newmont’s story. David Fry, previously Group Head, Global Projects, becomes Executive Vice President, Project Development, bringing experience from managing a large portfolio of projects at Rio Tinto and earlier engineering and operational roles at UGL and Origin Energy; his remit is to oversee disciplined development of Newmont’s highest‑return projects, ensuring that schedule, capital and risk are managed coherently across the global pipeline. In a sector where capital blow‑outs have repeatedly destroyed value, elevating project development to the top table is a strong signal that management intends to convert today’s exceptional cash generation into tomorrow’s production and cash‑flow growth without repeating past industry mistakes.
These management moves are landing at a time when Newmont’s financial engine is already running hard. 4Q25 and FY25 results showed the company “crushing” earnings estimates, with revenue up more than 20% year on year and free cash flow reaching a record US$7.3 billion, supported by strong gold prices and improving margins despite lower production volumes; the balance sheet swung to a net cash position of about US$2.1 billion, a sharp reversal from prior leverage concerns, and management reiterated its focus on margin expansion and robust free cash flow through 2026. In 1Q26, Newmont followed up with another record: roughly US$3.1 billion of quarterly free cash flow on about 1.3 million attributable gold ounces, keeping it on track for its full‑year guidance and underpinning a US$0.26 per‑share dividend declaration, while also announcing a multi‑year US$6 billion share‑buyback programme that further signals confidence in the durability of cash generation.
Overlaying this company‑specific strength is a constructive macro set‑up for gold and the broader precious‑metals complex. Since the sharp correction from February’s highs above US$5,600 per ounce, gold has retreated towards the low‑US$5,000s and worked off overbought conditions, with many leveraged positions washed out; technical analysts highlight that downside momentum has faded and that a double bottom near the April lows looks increasingly plausible, with a break above the dominant downtrend and the 200‑day moving average – currently in the roughly US$4,300‑4,450 zone – likely to mark confirmation that the correction has run its course. At the same time, expectations that the Federal Reserve will keep rates on hold while framing energy‑driven inflation as transitory, combined with easing oil prices and a reopened Strait, could weigh on the US dollar and yields, providing a classic catalyst for renewed strength in gold and the PGMs into year‑end.
Central‑bank demand is an important underpinning of this bull‑market thesis. A recent World Gold Council survey of 74 central banks found that 45% plan to increase gold holdings in the coming 12 months – the highest share since the survey began in 2018 – while only one expects to reduce reserves; emerging‑market and developing‑economy central banks account for most of the prospective buyers, with around 53% indicating they will add to gold, compared with 18% of advanced‑economy central banks. Many of these institutions are buying through domestic accumulation programmes, purchasing gold from local miners in local currency rather than spending scarce hard‑currency reserves, and some are shifting storage from London and other traditional hubs back to domestic vaults, signalling a structural and politically motivated re‑weighting towards gold that is unlikely to reverse quickly.
This physical buying has already helped propel gold prices to more than double over the past three years, and several high‑profile houses remain outright bullish. Strategists at major US banks continue to publish upside targets well beyond current spot levels, with some calling for prices above US$5,400–6,000 over the medium term if central‑bank accumulation persists and Western institutional and retail investors re‑enter the market in size; on this view, the recent drawdown is a correction within an ongoing bull market rather than the start of a new bear phase. Systematic CTA trend‑followers, many of whom turned short or flat during the March–April sell‑off, would be forced to cover if gold breaks back above key moving averages and volatility compresses, potentially transforming a measured recovery into a sharper upside move – precisely the kind of environment where a low‑cost, highly leveraged producer like Newmont tends to outperform underlying metal prices.
Newmont also has an under‑appreciated strategic option in Nevada via its partnership with Barrick. Barrick is progressing plans to spin out its North American assets, including Nevada Gold Mines, the Fourmile discovery and Pueblo Viejo, but documentation and recent commentary emphasise that Newmont retains robust rights in the Nevada joint‑venture agreements, including rights of first refusal and consent on any transfer of interests; reports suggest that Barrick will also rely on Newmont to help finance Fourmile, which it has characterised as a potential flagship tier‑one mine. Barrick’s CEO has spoken of the possibility of reaching an “early agreement” with Newmont over Fourmile, which independent studies describe as one of this century’s most significant high‑grade gold discoveries, with preliminary assessments pointing to the potential for hundreds of thousands of ounces of annual production at low all‑in sustaining costs – a scenario that could add a powerful incremental growth engine to Newmont’s already enviable portfolio if structured sensibly.
Summary
Newmont has just delivered record free cash flow – about US$7.3 billion last year and a further US$3.1 billion in 1Q26 – and moved into a net cash position while committing to a US$6 billion buyback, it is now aligning operations, technical functions and project development under a refreshed leadership team built from proven internal talent, and it stands to benefit disproportionately if gold resumes its uptrend on the back of strong central‑bank buying, a softer dollar and renewed investor interest. In addition, the company’s rights and potential collaboration with Barrick around Nevada Gold Mines and Fourmile offer meaningful upside optionality that is not yet fully priced into the stock.
On the risk side, Newmont still faces execution risk in integrating acquisitions and delivering projects on time and budget, its margins remain sensitive to any sharp reversal in gold prices or new cost inflation, and the Nevada joint‑venture dynamics with Barrick could prove complex if interests diverge.
Balancing these factors, for investors with a multi‑year horizon and tolerance for commodity‑cycle volatility, Newmont now looks attractively positioned as a core precious‑metals holding with both strong defensive attributes and credible growth levers, warranting an upgrade to a “Long” (BUY) stance as the gold and PGM bull market quietly reloads beneath the surface.
We maintain our HOLD rating on Newmont (NYSE, ASX: NEM) for now.
Disclosure: Interests associated with Fat Prophets hold shares in Newmont.
