
- The market: Thursday’s US sell-off erased Wednesday’s relief rally. We remain tactically bullish.
- The catalyst: The Fed meeting and midterms are behind us. The Middle East is the clearing event still ahead.
- The opportunity: Gold held up, Chinese equities look cheap and the RBA may be close to a pause.
- Report Spotlight: Grab (US: GRAB) and St Barbara (ASX: SBM).
Want the full picture? Explore Platinum membership →
The Verdict
Wednesday’s relief rally lasted barely a day. What caught my eye on Thursday was what held up as the chips came down. The S&P 500 fell 4.3%, but the equal-weight index lost closer to 2.9%. Bonds rallied and gold pushed back above $4,100. There was real capitulation in the air. We still see this as the finishing stage of a correction that began months ago. The Fed meeting and the midterms are behind us; what happens next in the Middle East could yet decide how we finish the year.
The S&P 500 broke support at 7,500. I would expect downside momentum to dissipate between the 200-day moving average near 7,300 and the next support level at 7,100. The earnings outlook remains constructive in my view, and the index now trades below 18 times earnings.
With Democrats taking both chambers of Congress, the White House has a stronger incentive to negotiate with Iran. Limited strikes are still possible. It is the prospect of de-escalation that could take a lasting risk premium out of oil.
The Calls
Oil — one clearing event remains. WTI rebounded 3% to US$90.80 on Thursday, but remains below its earlier trading range. I don’t see crude falling back to pre-war levels between US$50 and US$60, but we could see a new lower range between US$70 and US$80 traced out over coming months. This would be a bullish outcome for the markets.
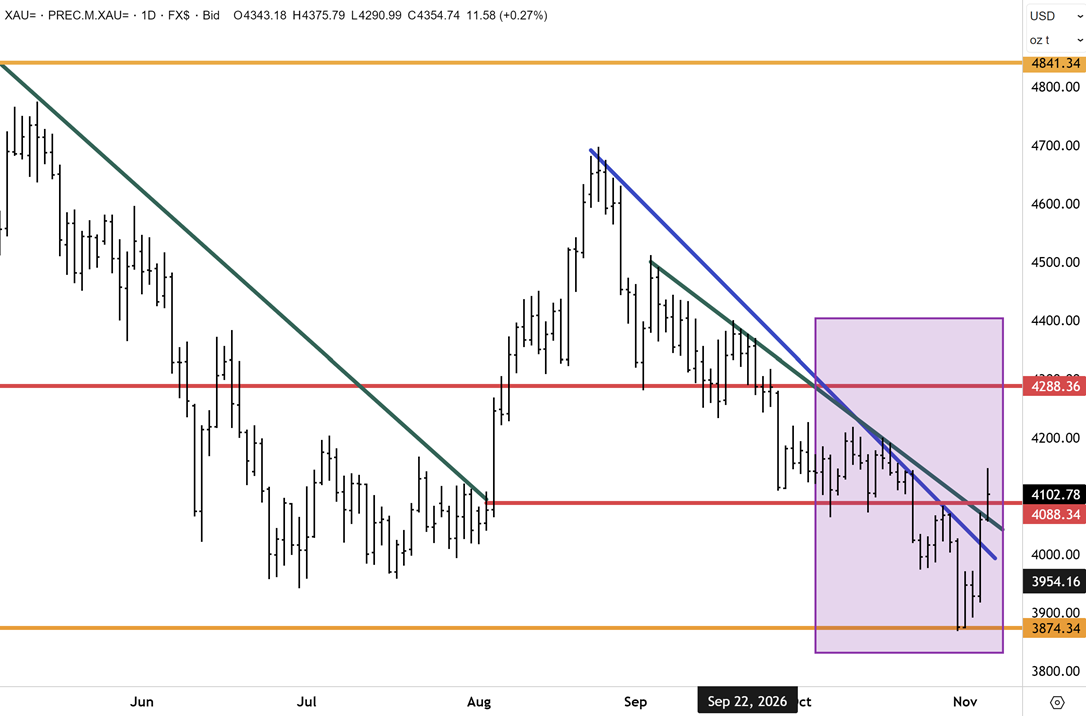
Gold — holding up as the chips came down. Gold surged more than 3% to above US$4,100 on Thursday, while gold and PGM miners bucked the broader sell-off. We need a decisive move above US$4,200 to strengthen the case that the correction is over. We are still looking for US$5,000 an ounce by year-end, or certainly in the early part of next year.
Central banks provide another tailwind. According to the World Gold Council, they bought a net 321 tonnes in the September quarter, the fastest pace since the end of 2024. That brought estimated year-to-date buying to 675 tonnes. The big move in gold last year was driven by central-bank and sovereign wealth fund buying — and this trend appears to be reasserting itself now.

China — deep value has emerged. The MSCI China Index trades at about 9.3 times forward earnings, with investor positioning relatively light. Government-backed buying and December’s Central Economic Work Conference could provide catalysts. Cheap valuations alone do not prevent further losses, but waiting for every economic concern to be resolved risks missing the window.
The Local
The RBA hiked, but it was a split decision. The fifth increase took the cash rate to 4.85%, with the board voting 6–3. Importantly, the statement removed references to further tightening. I have said that a fifth hike would be a mistake. I think this will be the last hike and the RBA will be cutting by this time next year.
The ASX 200 rallied 2.6% to 9,065 on Thursday, helped by resources and lower oil. By Friday morning, SPI futures were pointing to a relatively modest decline after the US sell-off. We still see decent prospects for the record high near 9,300 to be tested over coming months, with resources doing much of the heavy lifting.
Report Spotlight
Grab (US: GRAB)
Grab stood out to us during the US reporting season. The Southeast Asian mobility, delivery and financial platform’s third-quarter adjusted EBITDA rose 74% to US$237m, well ahead of consensus.
With Grab trading at around 14 times FY27 earnings estimates, value has emerged given expected earnings growth north of 40% a year over the coming years. Grab repurchased US$400m in September–October, with US$500m remaining under the programme.
US$3.30 is the level to watch. Grab has recently breached the primary downtrend at this level. Provided the stock sustains the breakout — our base case — an inflection might soon be confirmed.
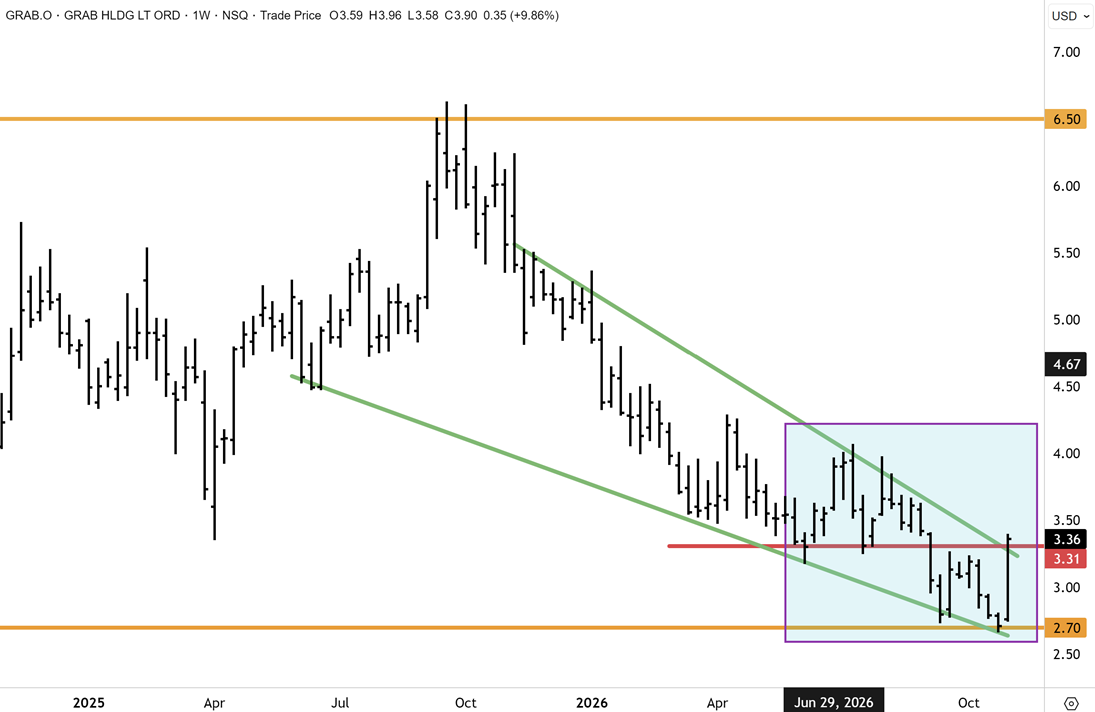
Grab — sustaining the break above US$3.30 would help confirm the turn.
Disclosure: We hold Grab across the international and Asia managed account portfolios and in the Global Contrarian Fund.
St Barbara (ASX: SBM)
St Barbara has given the green light to restart its Canadian Touquoy plant, processing already-mined rock into gold. That is a faster route to cash generation than building a new mine from scratch. Management also plans to buy back up to 100 million shares.
Cash is projected to rise towards A$1 billion over the coming year after asset divestments and royalty deals, against a market capitalisation of about A$900m.
After pulling back towards 74 Australian cents, 90–94 cents is the first resistance zone to watch. We remain confident that SBM will break above this level and retest A$1.10–1.20 over the coming year.
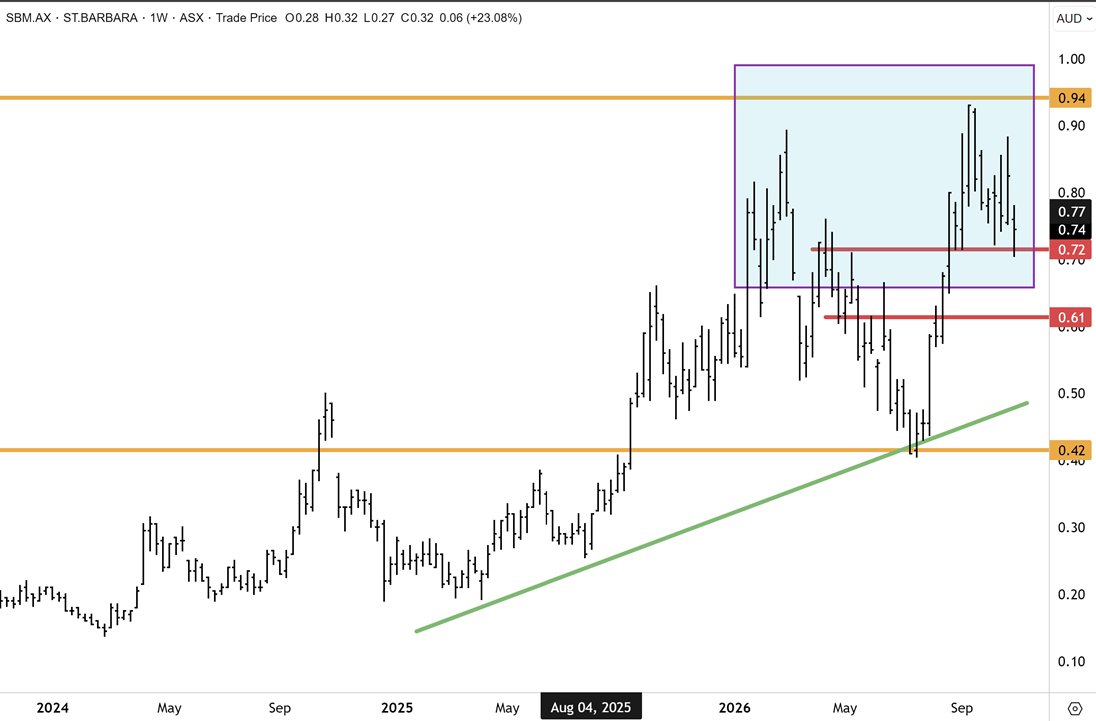
St Barbara — the first resistance zone is 90–94 Australian cents. Prices in Australian dollars.
The next test
We remain tactically bullish. The Fed meeting and the midterms are behind us. A deal in the Middle East would give the broadening rally a better chance to stick. Friday’s US payrolls report is still ahead of us as we write. A resilient labour market would lend support to the earnings outlook and to our case for a strong finish to the year.
For more on this week’s markets and where we see opportunity, sign in for the webinar and weekly podcast →
