
Digging In While Shedding Weight
South32 (ASX: S32) had a strong year, digging up more copper, zinc and manganese than expected across its mines. The company has agreed to sell off its aluminium business to Alcoa for up to US$5.6 billion, a deal still awaiting approval that would leave South32 focused mainly on metals used in electronics and batteries. Meanwhile, a major zinc and silver project in the US cleared a key approval hurdle, though construction won’t begin until next year and comes with a large price tag. With big changes still playing out and a new boss recently in charge, the company’s next moves remain worth watching closely.
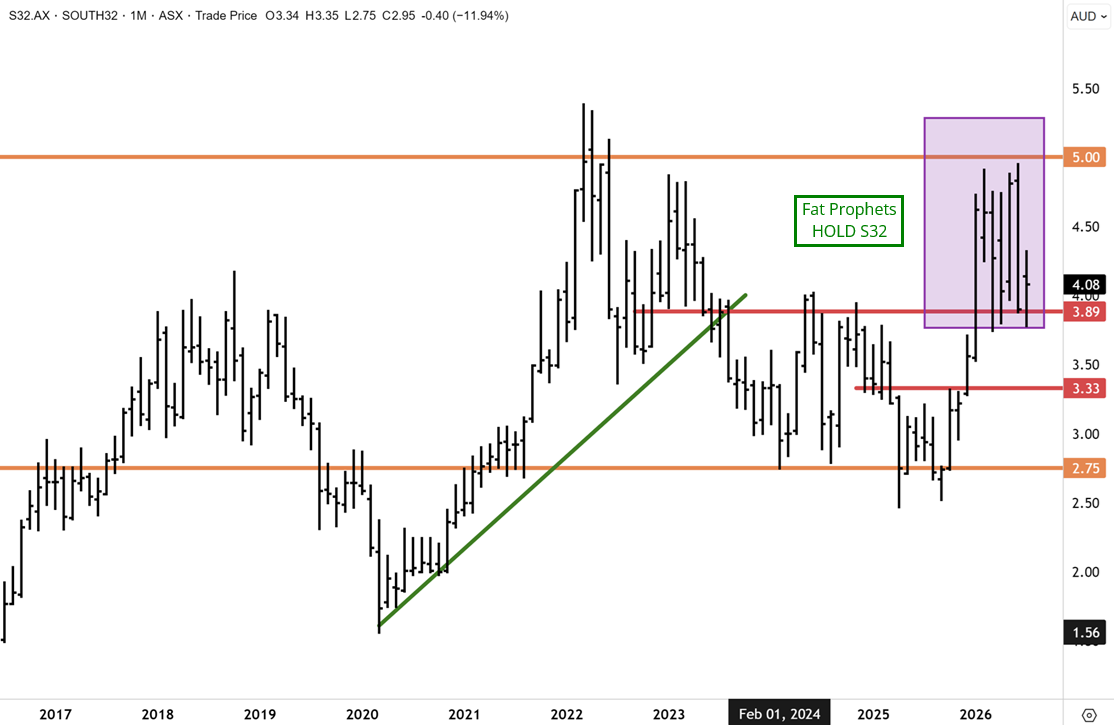
In our last tech update on the 2nd of July, we noted that “South32 has, since our last update, staged a decent upward dynamic off key support at $3.85 to close yesterday at $4.32. Whilst South32 remains rangebound below the four-year highs, we believe it is only a matter of time before the stock advances above overhead resistance at $4.80/$4.90 and, in time, establishes new record highs. We maintain a bullish outlook for commodities and base metals, where S32 is well-positioned across a range of base metals, and we will now have a more committed focus on copper.”
Since our last tech update on South 32 a few weeks ago, little has changed, with the shares consolidating within a range above key support at $3.80. Whilst South32 remains rangebound below the four-year highs near $5 and key support at $3.80, we believe it is only a matter of time before the stock advances above overhead resistance at $4.80/$4.90 and, in time, establishes new record highs. We maintain a bullish outlook for commodities and base metals, where S32 is well-positioned across a range of base metals, and will now have a more committed focus on copper.
Trading Update
For FY26, the Group exceeded production guidance across key operations, announced the sale of its aluminium value chain to Alcoa for up to US$5.6B, and advanced major copper and zinc growth projects at Sierra Gorda and Hermosa, together supporting a more focused upstream base‑metals strategy anchored in long‑life assets and a still‑solid balance sheet.
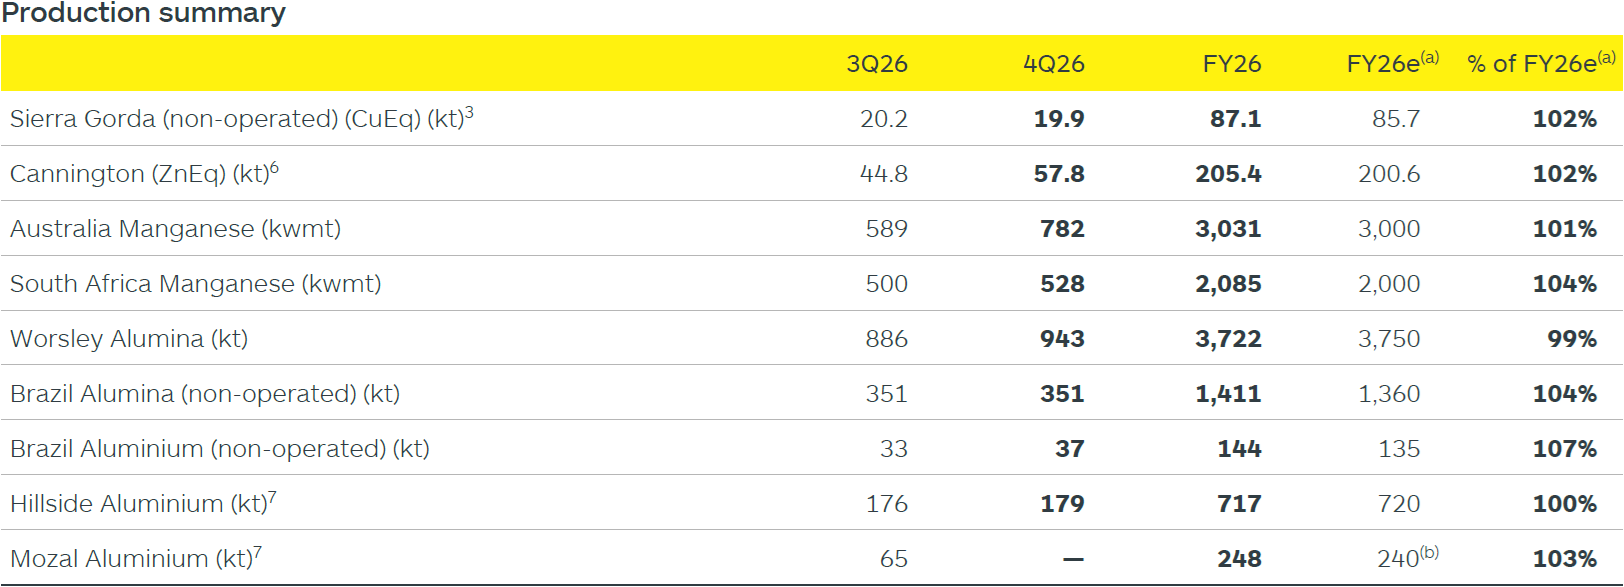
South32’s operational performance through FY26 was notably strong. Group production guidance was exceeded, with Sierra Gorda delivering 87.1kt of payable copper‑equivalent output versus guidance of 85.7kt (102%), Cannington producing 205.4kt of zinc‑equivalent versus 200.6kt (102%), Australia Manganese at 3,031kwmt versus 3,000kwmt (101%), and South Africa Manganese at 2,085kwmt versus 2,000kwmt (104%); aluminium operations also modestly outperformed, with Brazil Aluminium, Hillside and Mozal all at or above guidance. Quarterly sales volumes rose 15% in Q4 FY26 as final inventories at Mozal Aluminium were sold and rail access at Cannington was restored after prior weather‑related outages, contributing to a working‑capital unwind of about US$200M in H2 FY26 that added to cash generation.
 Source: S32 4Q26 Filing
The aluminium divestment marks a structural shift in the portfolio. On 1 July 2026, South32 announced a binding conditional agreement to sell its aluminium value‑chain assets (excluding Mozal Aluminium) to Alcoa Corporation for an implied enterprise value of up to US$5.6B, plus approximately US$1.2B of related rehabilitation provisions, with completion targeted for H2 FY27 subject to shareholder and regulatory approvals. Management’s message is clear: once complete, the sale is expected to unlock significant shareholder value and reposition South32 as a leading upstream base‑metals‑focused company, with around 85% of pro‑forma earnings coming from base and precious metals and roughly 55% production growth from approved projects, shifting the earnings mix away from alumina and aluminium and towards copper, zinc, manganese and silver.
The transition is underpinned by visible growth at flagship base‑metals assets. At Sierra Gorda in Chile, South32’s 45% share delivered record annual distributions of US$401M in FY26 and exceeded production guidance by 2% despite lower grades in Q4, as lower‑grade material was processed to supplement ore feed following weather‑related mine‑access impacts; payable copper sales grew 13% in Q4 as port congestion eased, and FY27 guidance of 90.2kt CuEq remains unchanged. Critically, the Sierra Gorda joint venture has approved execution of a fourth grinding‑line plant expansion, a roughly US$725M (100% basis) brownfield project over FY27–FY30 expected to increase processing capacity by about 25% to ~60Mtpa and lift copper‑equivalent production by around 30% from FY31, with South32 expecting its share of copper‑equivalent output to rise accordingly.
 Source: S32 4Q26 Filing
Hermosa, in Arizona, is the other major driver of the base‑metals pivot. South32 invested about US$710M of growth capital at Hermosa in FY26, continuing construction of the Taylor zinc‑lead‑silver project and completing the exploration decline at the Clark battery‑grade manganese deposit, and on 30 April provided an updated project case with Taylor’s initial operating life extended by five years to roughly 33 years, first production expected in H2 FY28, and total growth capex set at US$3.3B. Based on updated assumptions, Taylor is expected to deliver steady‑state EBITDA of around US$650M per annum and a net present value of approximately US$3.1B, reinforcing its role as a cornerstone low‑cost producer of zinc, silver and lead in a favourable jurisdiction. Importantly, on 7 July 2026 the US Forest Service issued the Final Record of Decision for Hermosa, completing the federal permitting process under the National Environmental Policy Act and clearing the way for a Notice to Proceed in Q1 FY27, materially de‑risking the project’s regulatory pathway.
Other base‑metals and polymetallic options are being quietly advanced. At Cannington, payable zinc‑equivalent production of 205.4kt in FY26 exceeded guidance by 2%, with a strong Q4 showing – a 29% increase in quarterly output – as underground mining rates recovered from earlier weather disruption and grades improved; development studies to extend mine life, including open‑pit options, are progressing, with a final investment decision targeted for H1 FY28. The Ambler Metals joint venture in Alaska, in which South32 holds 50%, began summer field‑season drilling and geotechnical work for the high‑grade Arctic polymetallic deposit, and Arctic has been accepted into the US FAST‑41 federal permitting programme, with a published timetable expected to bring greater predictability to approvals for what could become another long‑life copper‑zinc‑lead‑silver asset.
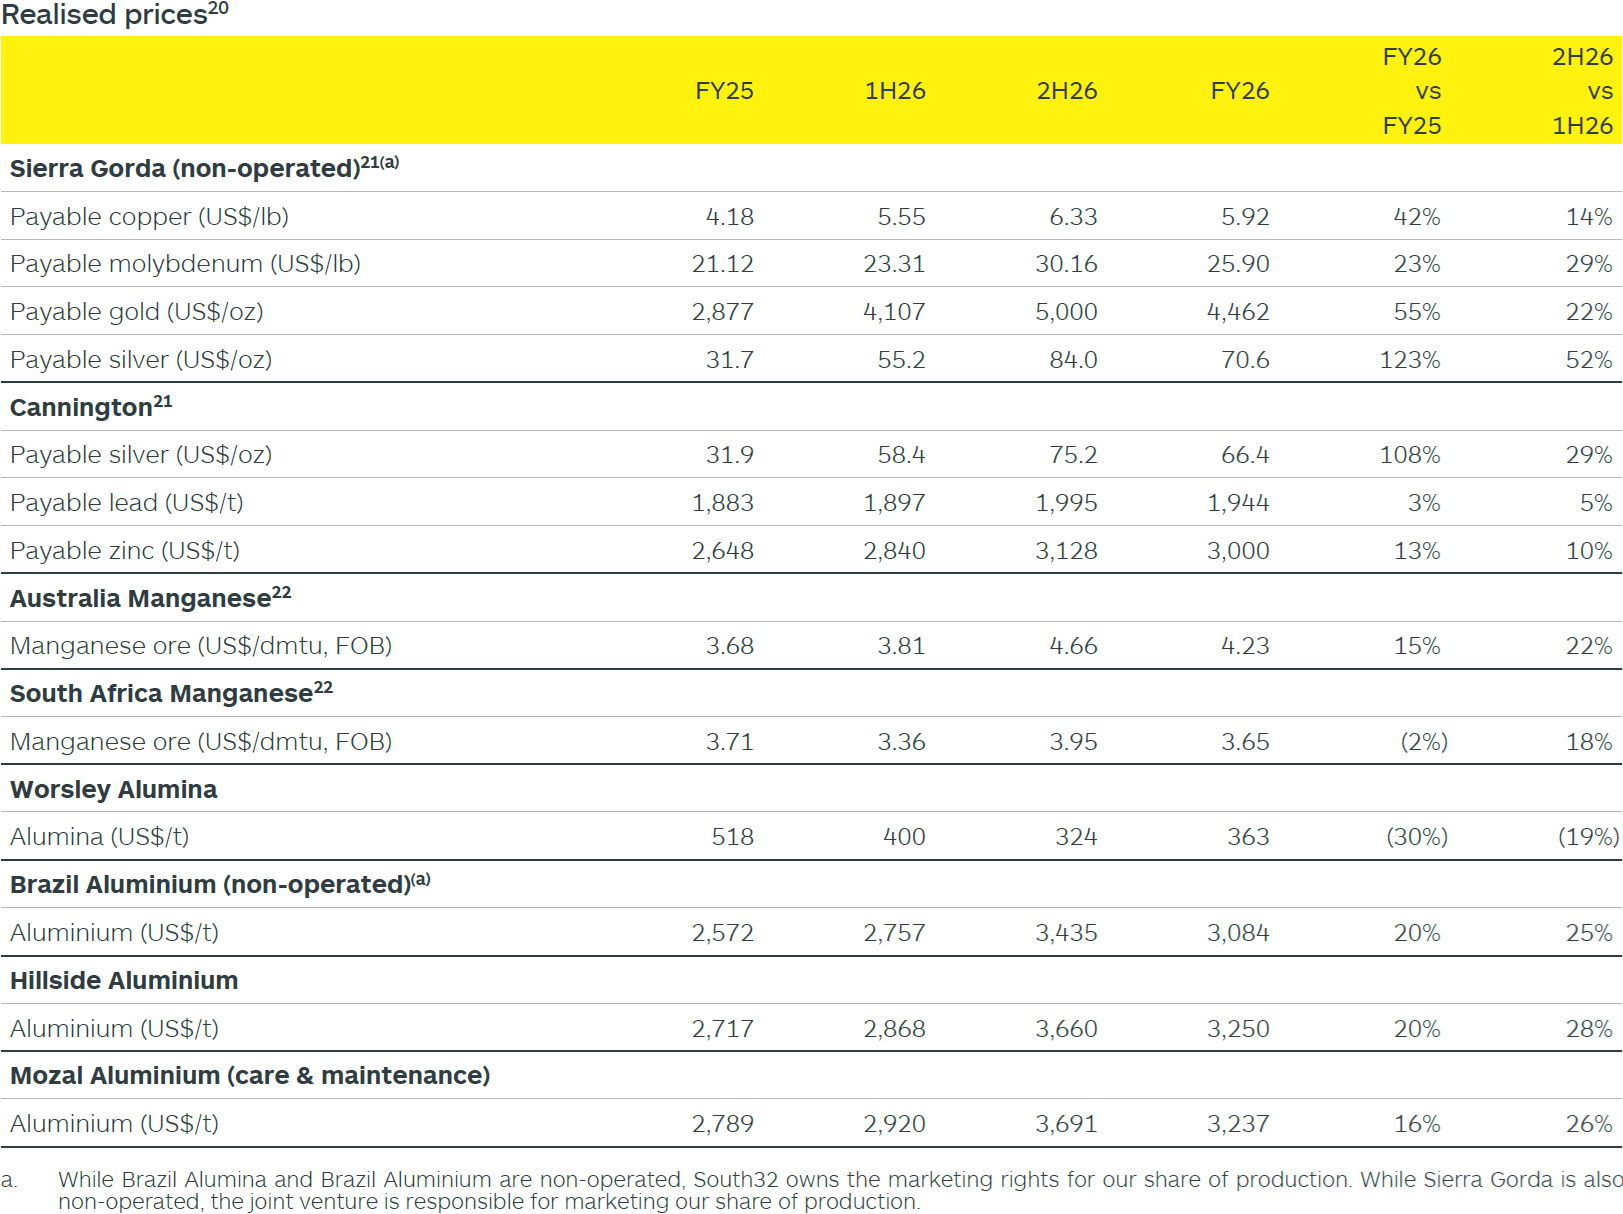
Manganese and alumina remain important cash contributors in the near term, even as the longer‑term mix shifts. Australia Manganese lifted saleable output to 3,031kwmt, in line with revised guidance, managing significant wet‑season and elevated water levels, and is working through approvals and infrastructure to manage water volumes before issuing revised FY27 guidance with the FY26 results; South Africa Manganese exceeded guidance with 2,085kwmt of production and a 6% quarterly uplift in Q4 after planned maintenance, supported by improved access to cost‑efficient rail logistics. Worsley Alumina and Brazil Alumina both delivered near‑record production, with Worsley at 3,722kt (99% of guidance) and Brazil Alumina at 1,411kt (104% of guidance), and while realised alumina prices were materially lower year‑on‑year, both operations maintained stable operating performance, supporting cash flow ahead of the aluminium sale.
Costs have been contained reasonably well despite macro and currency pressures. Management notes that operating unit costs across the portfolio have been “well controlled” in FY26, supported by stable production and ongoing cost‑efficiency efforts, even as Middle‑East conflict has driven higher raw‑material and freight prices and producer currencies have strengthened; Sierra Gorda’s FY26 operating unit cost is expected to be about 10% above guidance due to the timing of a one‑off workforce payment and higher diesel prices, while Cannington’s unit cost is expected roughly 10% below guidance thanks to higher ore throughput offsetting higher royalties and a stronger Australian dollar. Australia and South Africa Manganese are expected to come in modestly above guidance on unit costs – around 10% and 5% respectively – reflecting diesel and currency effects, while Worsley Alumina and non‑operated alumina and aluminium assets are expected to broadly match first‑half cost profiles, reinforcing that the cost base is not running away from the company’s control.
Capital management and balance‑sheet discipline have continued alongside the pivot. In FY26, South32 received US$503M of net distributions from equity‑accounted investments – US$401M from Sierra Gorda and US$102M from its manganese businesses – and invested about US$325M in Group capex, excluding EAIs and Hermosa, alongside US$710M at Hermosa and US$30M of capitalised exploration; tax payments totalled US$285M, and US$327M was returned to shareholders through US$292M of fully‑franked ordinary dividends and US$35M of on‑market buy‑backs, leaving its US$2.6B capital‑management programme 92% complete with US$209M still to be returned ahead of February 2027. Additional lease liabilities of roughly US$115M were added, and one‑off costs related to Mozal’s transition to care and maintenance – about US$33M in restructuring and US$89M in non‑cash inventory write‑downs – will be excluded from underlying earnings, while the FY26 underlying effective tax rate is expected around 33%, reflecting the group’s jurisdictional mix and royalty‑related taxes.
Summary
South32’s combination of above‑guidance FY26 production, the agreed aluminium sale to Alcoa, and visible growth at Sierra Gorda, Hermosa and Ambler supports a constructive medium‑term outlook on the shares, but the scale and timing of the transition justify our Neutral outlook for now.
First off, exceeding production guidance across copper‑equivalent, zinc‑equivalent, manganese and aluminium units, coupled with record distributions from Sierra Gorda and a clear, de‑risked path for Taylor at Hermosa – including a 33‑year mine life, projected steady‑state EBITDA of about US$650M and a net present value near US$3.1B – underpins a credible move towards a more profitable base‑metals‑weighted portfolio; the aluminium sale to Alcoa at an implied enterprise value of up to US$5.6B plus US$1.2B of rehabilitation provisions, and the continued strength of the balance sheet and capital‑management programme, add further support.
On the more cautious side, the transition will involve execution risk across multiple projects, exposure to commodity‑price cycles and permitting timetables, and a period where earnings from divested aluminium assets will roll off before new base‑metals volumes and cash flows fully ramp, while operating‑cost pressures from energy, freight and currencies remain a live issue.
All in all, South32 offers appealing leverage to long‑life copper, zinc, manganese and silver growth with a clearer strategic focus and robust capital discipline, but until investors see more detailed FY27 guidance, final terms and uses of proceeds from the Alcoa transaction, and early delivery against Hermosa and Sierra Gorda expansion milestones, a rational HOLD stance is appropriate, viewing the name as a core base‑metals exposure rather than an immediate re‑rating story at this stage of the cycle.
In any case, we maintain our HOLD rating on South32 (ASX: S32, LSEG: S32). For those already positioned, South32 remains a core minerals holding, well-placed to ride the next wave of global metals demand and battery supply chain reconfiguration.
Disclosure: Interests associated with Fat Prophets hold shares in South32.
