South32

S32
October 23, 2026 FAT-AUS-1293
AUD4.36
Speculative
high
Buy
South32
Latest Closing Price: AUD4.36
South32 Limited is a mining and metals company. Its segments include Worsley Alumina, focused on integrated bauxite mine and alumina refinery in Australia; Brazil Alumina, which operates Alumina refinery in Brazil; Brazil Aluminium, which operates Aluminium smelter in Brazil; Hillside Aluminium, which operates Aluminium smelter in South Africa; Mozal Aluminium, which operates Aluminium smelter in Mozambique; Illawarra Metallurgical Coal, which operates underground metallurgical coal mines in Australia; Australia Manganese, which is an integrated producer of manganese ore and alloy in Australia; South Africa Manganese, which is an integrated producer of manganese ore and alloy in South Africa; Cerro Matoso, which is an integrated laterite ferronickel mining and smelting complex in Colombia; Cannington, which operates silver, lead and zinc mine in Australia; Hermosa, which is engaged in base metals exploration and development option in the United States; and South Africa Energy Coal.
Market Capitalisation: AUD19.55b

Funding Tomorrow from Today’s Copper

South32’s (ASX: S32) September quarter supports its shift towards copper and zinc: existing mines are contributing cash while new projects advance, and the approved aluminium sale offers a way to finance growth without relying entirely on future commodity-price gains.

South32 earns the margin between mineral sales and mining, processing and transport costs. It also receives distributions from jointly owned operations, including Sierra Gorda in Chile. What makes South32 attractive for shareholders is a combination of current earnings and additional production under development. We think the latest quarter strengthens that case, although Cannington’s weak start means the group still needs an operating recovery alongside its longer-term investment programme.

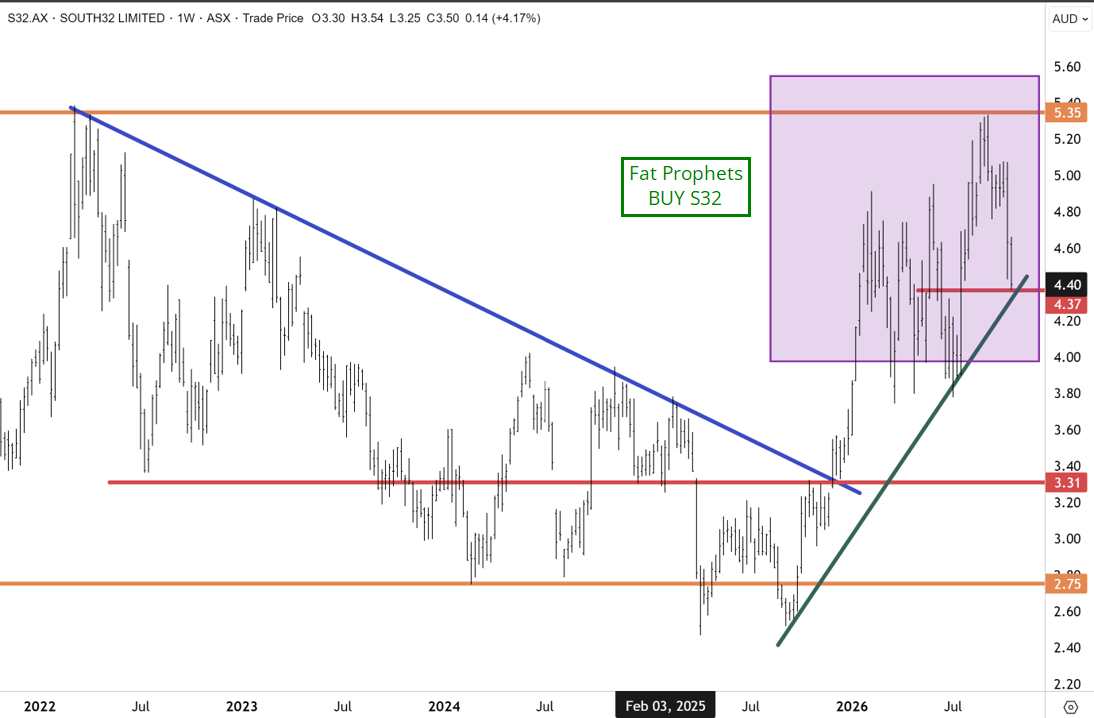
Turning to the charts and South32 has failed to sustain the breakout to new record highs flagged in our last update. Nevertheless, we remain of the view that it is only a matter of time before S32 advances into new record territory, given our structural bullish outlook on global commodities, base metals, and copper. On the charts, S32 has corrected sharply toward key technical support along its primary uptrend line near $4.40, leaving the shares looking heavily oversold at current levels. We maintain our broader constructive stance on commodities and base metals, an environment where South32 remains exceptionally well-positioned across the resource complex due to its increasingly committed strategic focus on copper.
Trading Update – 1Q27

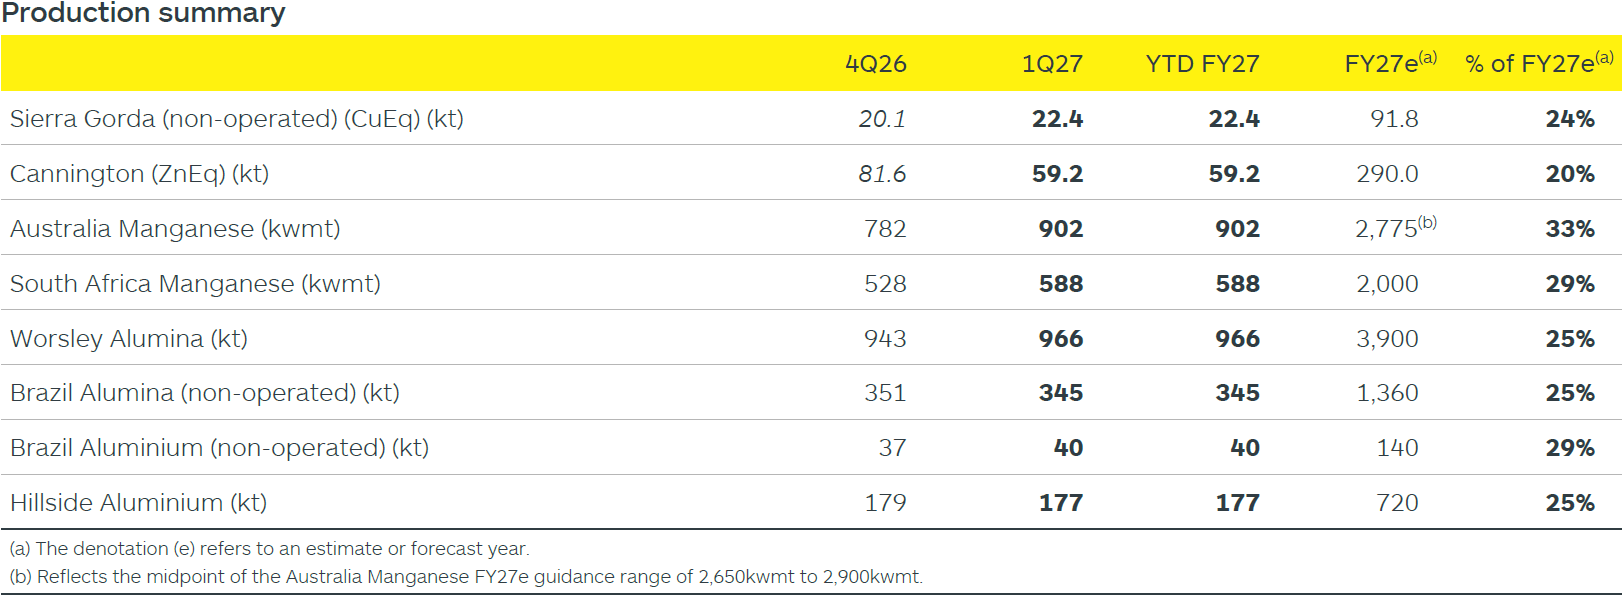
Looking at the numbers, Sierra Gorda supplied the clearest financial support, distributing US$153 million to South32 during the quarter. Its share of payable copper production rose 17% from June to 18,700 tonnes, although growth was only 2% year-on-year. The cash distribution is more immediately useful than the production headline: it helps fund group expenditure without requiring an equivalent increase in borrowing. It is also a record quarterly receipt – a welcome result in our view.

The mine also offers growth through an established operation. Work began on a fourth grinding line which is expected to increase processing capacity by approximately 25%, with first production targeted for mid-FY30. Processing more ore could lift copper sales, depending on the metal content and recovery achieved. This gives South32 an expansion opportunity alongside a mine already contributing cash, rather than requiring another entirely new operation and export chain.
Source: S32 1Q27 Filing

Hermosa is the larger immediate funding commitment. South32 spent US$197 million on growth construction during September, plus approximately US$15 million of related lease payments. Completion of federal permitting removed an important hurdle, and both Taylor shafts are expected to reach the primary production level in December. These are useful construction milestones, but the project still consumes cash before producing zinc, lead and silver for sale.

The aluminium disposal can help bridge that investment period. Shareholders approved the transaction on 15 October, with completion expected in the first half of calendar 2027, subject to remaining conditions. South32 finished September with US$297 million net cash, before paying its US$242 million final dividend. Approximately US$300 million of cash was covered by the sale’s locked-box arrangements. We therefore would not treat the quarter-end headline as an unrestricted pool available for further distributions.

Cannington provides the main opportunity for near-term earnings recovery. Problems supplying material used to refill mined underground areas restricted access to planned ore. Lower-grade stockpiles kept the mill running, but produced less saleable metal; zinc-equivalent output fell 27% from June. Upgrades to the delivery system should improve mining rates, and annual guidance remains unchanged. Restoring access to better ore would improve revenue without requiring a corresponding increase in mill throughput.

Turning to the valuation, South32 trades on approximately 12.5x FY26 statutory basic earnings and offers a 3.1% trailing ordinary dividend yield, using US$0.7025 per Australian dollar to compare the price with US-dollar earnings and dividends. These historical figures are not a normalised forecast for the business after the aluminium sale. In our view, the valuation reflects a profitable miner but may give insufficient weight to the combination of Cannington recovery and future base-metals production – an opportunity for value investors here. Successful project delivery and disciplined use of sale proceeds would justify a higher valuation by improving future earnings and reducing funding pressure.

A prolonged Cannington shortfall would reduce cash generation while Hermosa continues absorbing funds. If aluminium-sale completion also slipped, South32 would have less flexibility to balance construction spending, debt and shareholder returns.

We will assess December-quarter mining recovery, Taylor’s shaft milestones and the remaining sale approvals. The half-year results should also clarify Cannington’s potential mine-life extension and the cash available after development spending.

Summary

At around 12.5x historical earnings provides a reasonable starting valuation for an investment in South32 with both an operating recovery and longer-term production growth ahead. Sierra Gorda contributes cash today, while the aluminium disposal could help finance the next stage. Cannington must recover and Hermosa spending must remain controlled; we will assess both before treating stronger future dividends as part of the return.

We maintain our BUY rating on South32.

Disclosure: Interests associated with Fat Prophets hold shares in South32.

DISCLAIMER
Fat Prophets has made every effort to ensure the reliability of the views and recommendations expressed in the reports published on its websites. Fat Prophets research is based upon information known to us or which was obtained from sources which we believed to be reliable and accurate at time of publication. However, like the markets, we are not perfect. This report is prepared for general information only, and as such, the specific needs, investment objectives or financial situation of any particular user have not been taken into consideration. Individuals should therefore discuss, with their financial planner or advisor, the merits of each recommendation for their own specific circumstances and realise that not all investments will be appropriate for all subscribers. To the extent permitted by law, Fat Prophets and its employees, agents and authorised representatives exclude all liability for any loss or damage (including indirect, special, or consequential loss or damage) arising from the use of, or reliance on, any information within the report whether or not caused by any negligent act or omission. If the law prohibits the exclusion of such liability, Fat Prophets hereby limits its liability, to the extent permitted by law, to the resupply of the said information or the cost of the said resupply.

Funds Management – In addition to the listed fund FPC, Fat Prophets Pty Ltd manages the separately managed accounts, namely Concentrated Australian Shares, Australian Shares Income, Small Midcap, Global Opportunities, Mining & Resources, and Asian Shares. These SMAs are managed under their own mandates by the fund managers, and this is independent to the research reports.

Staff trading – Fat Prophets Pty Ltd, its directors, employees and associates of Fat Prophets may hold interests in many ASX-listed Australian companies which may or may not be mentioned or recommended in the Fat Prophets newsletter. These positions may change at any time, without notice. To manage the conflict between personal dealing and newsletter recommendations the directors, employees, and associates of Fat Prophets Pty Ltd cannot knowingly trade in a stock 48 hours either side of a buy or sell recommendation being made in the Fat Prophets newsletter. Staff trades are pre-approved by an appointed staff trading compliance officer to ensure compliance with the staff trading policy.

For positions that directors and/or associates of the Fat Prophets group of companies currently hold in, please click here.

Stock Disclosure

ASX- Listed Australian stocks:

A1M, AAC, ABX, ABY, ADI.AU, AKE, ALK, AMC, AMI, ANN, ANZ, APA, ARB, ASM, AZS, BFC, BFC.AU, BHP, BKL, BLD, BOQ, BUB, BWP, CAT, CHC.AU, CHN.AX, CKF, CNR, COF.AX, CQE.AU, CSL, DHG, DMP, DXS.AU, ECF.AX, EHE.AUX, ELD, ENN.AX, ESS, EVN.AU, FAL, FATP.AX, FID, FMG, FPC.AU, FPP, GBS, GOLD, GOR.AU, GPT.AU, HUB, IDX, IGO, IPL, JHC.AX, JHX, KRR, MCR, MPL, NAB, NCM.AU, NEC, NML, NSR.AU, NST.AX, NUF, NXM, ORA, ORI, PAN, PAR.AU, PPS, PRN, QAN, QBE, RED, RIO, RXL, S32, SBM, SCG.AU, SCG-2, SFR, SGP, SHL, SLR, SRG, SRV.AU, SSPG-2, SSR, STO, SUN, SVY, TLS, TPG, TRS, TWE, VCX, WBC, WDS, WHC, X64, PDN, GNC, MGR, TYR, ATOM, 29M, RRL.AU, STO.AX, WDS.AX & GMD.AX

International stocks:

3382, 3690, 5930, 6506, 6954, 8058, 9432, 1128.HKE, 1818.HKE, 1821.HK, 1876.HKE, 1928.HKE, 1972.HKE, 2282.HKE, 2840.HKE, 2883.HKE, 3289.TKS, 3690.HKE, 388.HKE, 435.HK, 5929.TKS, 6367.TKS, 6481.TKS, 6758.TKS, 683.HKE, 69.HKE, 700.HKE, 7167.TKS, 7186.TKS, 7974.TKS, 823.HK, 8306.JP, 8316.JP, 8331.T, 8411.T, 8604.TKS, 8604-2, 8801.JP, 8804.TKS, 9684.TKS, AAL, AAPL.NAS, ABX.TSX, ACA.PAR, AIR, AMH.NYS, AMS, AMS.MAD, ANGPY, ANTO, APF, ARF, AT1.ETR, ATVI, ATYM, AUTO.LSE, AV, AVB.US, BA, BABA.NYS, BAC, BARC, BBOX.LSE, BGFD, BHP.NYS, BHR.NYS, BIDU.NAS, BKIA, BMW, BN, BNP.PAR, BP, BT.A, BXP.NYS, C, CAST.SE, CAT, CCH, CCL.LSE, CDE.NYS, CDE.US, CEY, CHL, COL.ES, CQR, CSCO, CSGN, CUZ.NYS, CVO.PA, DGE, DHC, DHI, DIS, DIS.NYS, DLR.NYS, DOM.LSE, ECMPA.AMS, ENAV-uk, ENTRA.OSL, ENX.PAR, EQIX, ESS.US, EXR.NYS, EZJ, FDX, FRES.LSE, G24, GDX.LSE, GDXJ.LSE, GDXJ.US, GEMD, GLD.ARC, GLEN, GOCO, GOLD.NYS, GOOG, GRG, GSK, HDB, HEIA.AMS, HL, HLT.NYS, HMY, HMY.NYS, HSW, HUFV.SE, IAG, IBN, IMG, IMPUY, ITRK, ITV, JHX.NYS, JP.8308, KGC, KIM.US, KNEBV.HEL, KWS, LEG.ETR, LEN, LGEN, LLOY, LRE, LSE, LVMH, MC.PAR, MCRO, MCRO.LSE, MKS, MOL, MONY, MRL.ES, MTN.NYS, NEM, NG, NSR, NWH.U.CA, NWH.UN.TSX, OXY, PETS, PG, PHE, PHE.LSE, PLATJPN, PLD.US, PLEF, PLG.CA, POLY, PPH, PSA.NYS, PZC, RB, REL, RELX, RI, RIGD, RIGD.LSI, RING, RMV.LSE, RNK, RR, SGE, SGRO.GB, SHEL, SIL, SKT, SKT.US, SLP, SMDS, SMI, SMSN.LSI, SN, SNE, SPG.US, SPK, SRC.US, STAY.NAS, SYY, TGYM, TJX.NYS, TME, TRNO.US, TSM, TTWO, TWR, UBER, ULVR, UMH.NYS, VER, VNO.NYS, VOD, VOW, VTR.US, WELL.K, WMG.NAS, WYNN, XERI.PK, XOM, YTRA, YUMC, ZG.NAS, URA, HEM.SE, 9888.CN, 9988.HK, 7163.JP, CDE.US, GENI.GB, PDN.AX, RIOT.US & ZG.US